The financial crisis and ensuing regulatory remedies may have permanently shifted the lending landscape, but not all lenders were damaged or displaced. The credit union industry in particular has benefitted – shifting public sentiment, a push to raise their profile in the eyes of consumers, and even some of the newer financial regulations have resulted in credit unions moving in on the turf of banks and mortgage companies.
According to data from The Warren Group, publisher of Banker & Tradesman, Massachusetts credit unions made 2,943 of the 98,842 purchase loans statewide in 2005. In 2010, credit unions made 2,817 of the 54,093 total loans across the Bay State. And in 2015, credit unions made 4,739 out of the 71,460 loans statewide.
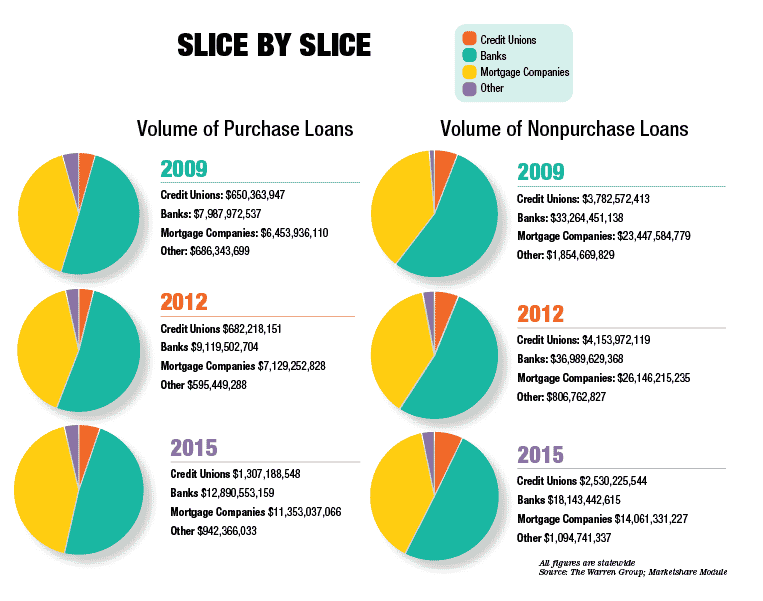
As a lender category by volume, credit unions captured about 4 percent of the purchase market statewide in both 2009 and 2012, making $650.4 million and $682.2 million worth of loans, respectively. Then last year, credit unions made $1.3 billion purchase mortgages, this time capturing 5 percent of the pie.
They did a little better with non-purchase loans, however.
Credit unions made $2.53 billion in non-purchase loans last year, or about 7 percent of all such loans. They made about $4.2 billion, or about 6 percent, of all non-purchase loans in 2012, arguably in the thick of the refinance boom. In 2009, they also captured about 6 percent of non-purchase residential loans, for a total of about $3.78 billion as a lender category.
By way of comparison, banks still captured about 51 percent of the non-purchase market and mortgage companies captured 39 percent last year. Credit unions aren’t putting their larger competitors out of business, but they are, slowly and surely, carving out a bigger slice of the pie.
Credit unions and their cheerleaders will tout those famously competitive interest rates and high-touch service, but that’s not exactly the whole story.
Regulatory Relief
 In more than one way, credit unions benefitted from the financial crisis. Post-financial crisis regulation leveled the playing field between credit unions and their larger competitors, and consumer dissatisfaction with the biggest of banks drove many to seek out the not-for-profits as banking alternatives.
At the same time, credit unions have also been quietly expanding their suite of mortgage products and raising the industry’s profile as more than just an auto lender.
“For decades now, we’ve been fighting this fight, trying not to be known as auto lenders. It’s creating awareness that we’re much more than an auto lender,” said Caleb Cook, vice president of mortgage lending at Digital Federal Credit Union.
“In our advertising specifically, we’ve integrated all of our services so that when it comes to the DCU brand, you don’t just think auto loan. Even smaller credit unions that don’t have the same advertising budgets are doing a lot more to promote their brand as home lenders,” he said.
Digital Federal Credit Union originated $47.3 million in purchase volume in 2009, $54.8 million in 2012, and $119.4 million in 2015.
DCU has “significantly” increased its residential lending staff, both mortgage loan originators and back-office support staff, to generate and keep up with the increase in volume, Cook said. He also credits the SAFE Act of 2008 with making credit unions a more desirable place for mortgage loan originators to work
Other credit unions also reported having increased their residential lending staff, both to generate and support the volume of new business they’ve been doing.
“We’ve increased the size of both our outside origination team and then, as volume increases, you need to have the support staff to accommodate that volume,” said Brian Sousa, senior vice president and chief lending officer at Jeanne D’Arc Credit Union.
It’s apparently worked, too. According to The Warren Group’s data, Jeanne D’Arc Credit Union originated about $21.6 million in purchase mortgages in 2009, $24.8 million in 2012, and $115.5 million last year.
Or consider Metro Credit Union, which originated $33.1 million in purchase loans in 2012 and $95.4 million in purchase loans last year.
President and CEO Robert Cashman said that Metro has also increased its mortgage lending staff, sometimes even drawing loan officers away from big banks and mortgage companies.
 “We’ve attracted a good number of mortgage loan officers primarily due to the fact that they’ve heard about our back office shop, our support and our reputation,” he said. “I think anyone wants to work for an organization that has a good reputation and can walk the walk.”
Credit unions also say they’ve worked on filling out their complement of mortgage products. Once upon a time, a credit union might have offered two products – a 30-year fixed and a 15-year fixed – but that’s no longer the case.
“For us to be successful, we feel that we need to have a really great mix of adjustable and fixed rate products to make sure we can serve all of our members and communities,” Sousa said.
“A lot of us have said we have to offer a full array of residential mortgage products,” said Tom Gray, senior vice president of lending at Workers Credit Union. “We offer VA, FHA, 3 percent down and conventional, ARMs and fixed.”
Gray said that additionally, the financial crisis shook a few other competitors out of the market. Some mortgage companies were merged out of existence or decided to close up shop rather than deal with new regulations, and that opened up an opportunity for credit unions to capture consumers’ attention.
The Human Touch
But where credit unions might really step up their game is within the local Realtor community.
Though credit unions tout their increased efforts at reaching out to and networking with real estate professionals, several Realtors who Banker & Tradesman reached by phone said they haven’t been personally hearing from the credit unions.
Hans Brings, a Realtor with Coldwell Banker in Waltham, said that he has seen more pre-approvals from credit unions, but they haven’t been flooding his inbox the way that banks and mortgage companies do.
Lisa Howitt, a Realtor and broker associate with Century 21 Sexton & Donohue, reported something similar, though she added, “I did just have a transaction with a buyer that was preapproved with a credit union. Everything went smoothly, but I haven’t been personally contacted by credit unions asking for my business or asking them to keep me in mind.”