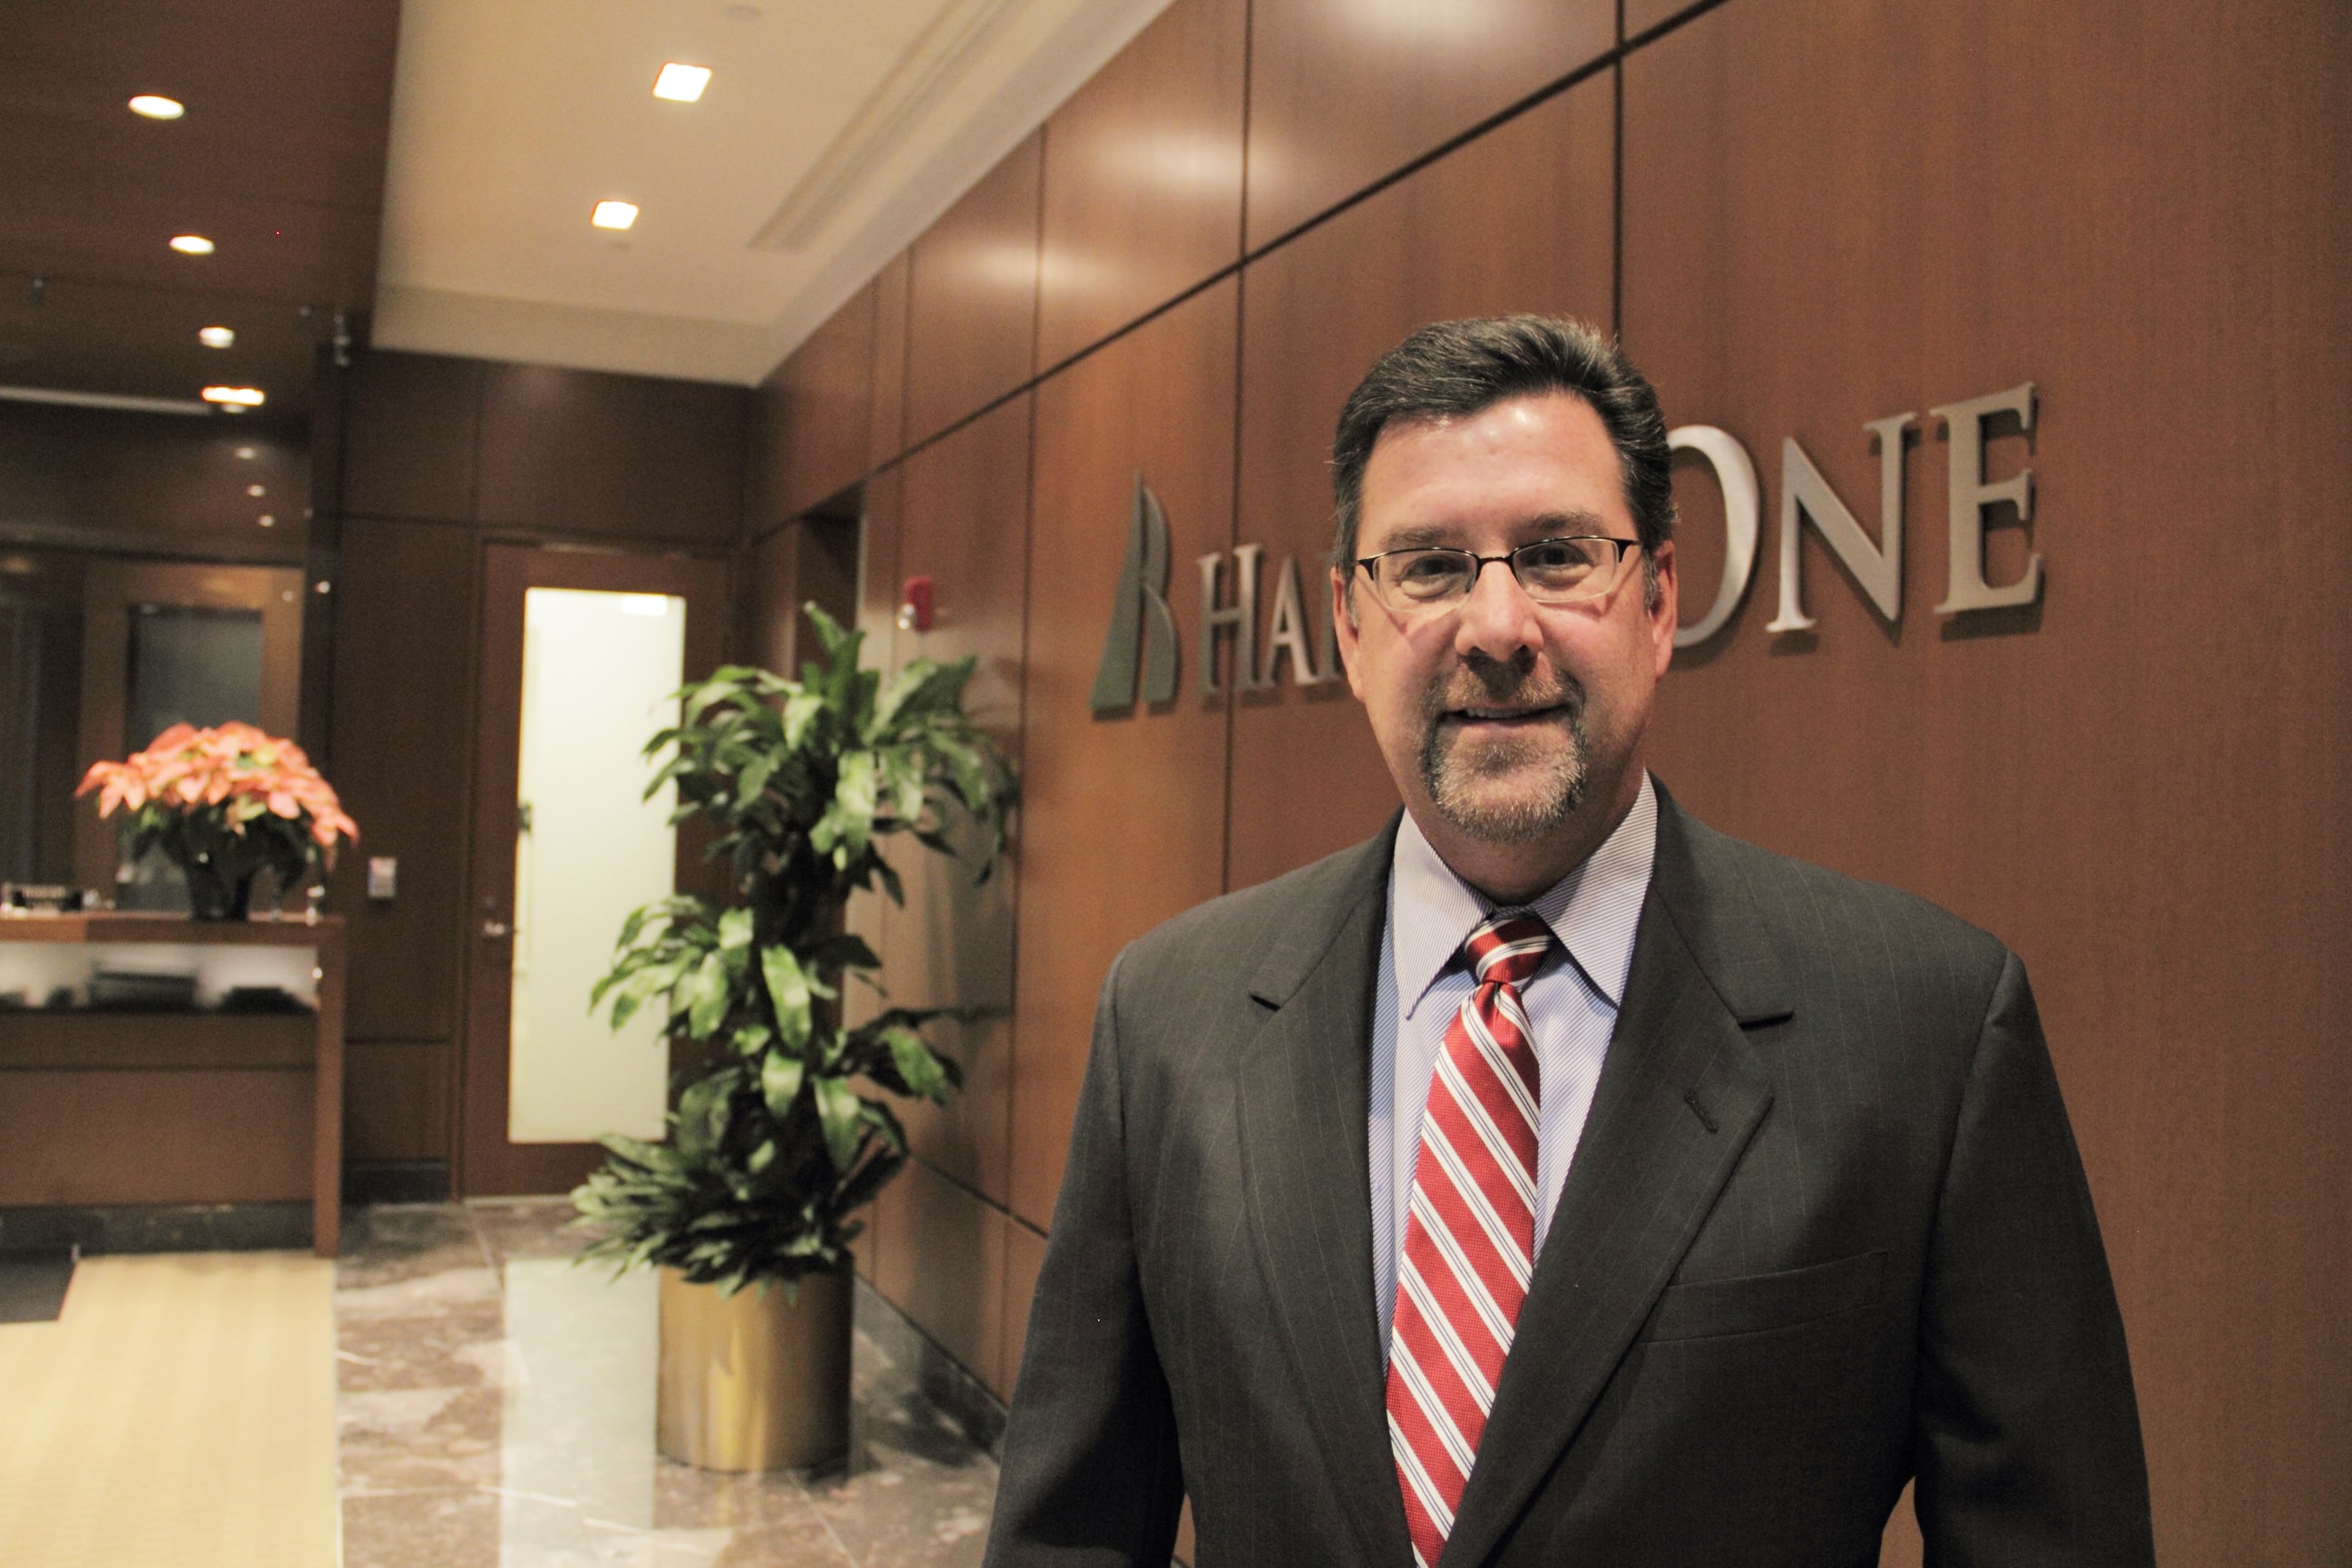
Pete Makowiecki
Pete Makowiecki
Title: Senior Vice President, Residential Lending, HaborOne Bank
Age: 55
Experience: 29 years
Pete Makowiecki found his way into mortgage banking in 1989 when he took on a position at Fleet Bank, in the mortgage banking division. He retired early after the sale of a Dallas-based mortgage banking company he headed, only to realize that he missed the pace of the business. In 2013, Makowiecki came out of retirement to join HarborOne on the very day of its conversion to a bank charter, where he was immediately tasked with tripling the size of its mortgage banking business.
Q: Can you talk about your growth so far, including your recent acquisition of Merrimack Mortgage Co.?
A: We were going to [grow the mortgage business] in a number of different ways, but one of those ways, clearly, to get that kind of pace of growth, is through mergers and acquisitions. We were going on this multipronged approach, but we were lucky enough to run into Merrimack Mortgage up in New Hampshire. … They basically cover New England, so not only did we get a mortgage banking operation that was 10 times our size, it provided us with geographic expansion that is broadly another corporate goal. … It was a huge step in the right direction for us.
What they also brought was a significant amount of mortgage banking fee income, and that significantly added to the bank’s mortgage banking fee income, even in the six months we’ve had it. It’s really turned out to be a valuable acquisition, accretive from day one.
Q: Has the regulatory environment challenged that growth for you?
A: Like everybody, absolutely, the regulatory environment and the continued, almost onerous, regulatory requirements, have been a challenge. We’ve spent a tremendous amount of time and energy in training and getting up to speed. … Not only is it a mental burden, but it’s a financial cost as well.
Being a glass-half-full kind of person, I think it provides opportunity, because there’s a lot of smaller institutions, let’s call them the mortgage bankers or brokers, that can’t really afford to carry that burden anymore. I think it does offer a company like ours the opportunity to pick up good, quality operations that have just thrown their hands up [and said] “I don’t want to deal with it, it’s too complicated.” For those committed to the mortgage business, the mortgage space is going to be a good space to be in, my view is, for at the least the next five years.
Q: Why?
A: With the Great Recession starting in 2008, it’s been a tough business. It created a lot of the regulatory framework that exists today, good or bad. I don’t know that the regulatory framework has made it safer or a better business, necessarily, but if you look at the demographics and what’s going on, all the trends are gradually improving. On a nationwide basis, certainly, foreclosures are dropping – Massachusetts is kind of an anomaly – but generally, nationwide, foreclosures are dropping, home prices are now appreciating, a significant number of people now have real equity in their home.
Housing starts and new home sales and everything has got an upward slope to it. I like that because it’s slow and steady. It’s not what we experienced in the early 2000s, which was just a skyrocketing escalation of property values.
I think lending is more rational today. Maybe regulation had something to do with that when people realized mistakes were made in the early 2000s. I think it’s just a more rational, well-run business today and more people are starting to get back into it.
Q: What’s on the agenda for 2016 at HarborOne?
A: The first half of the year, as we look at it, our focus is going to be twofold: we want to continue to integrate the Merrimack operation. We’ve had six months under our belt, and it’s not that we’re dramatically changing the business model or anything like that, just making sure we’re comfortable with the key components of that integration. That’s a big part of the first half of ’16.
Then our focus from a business perspective is going to be on first-time homebuyers, purchase money market and making sure that we do an even better in our community reinvestment front. A lot of CRA lending is first-time homebuyer lending, but that’s clearly where we’re going to be spending our marketing dollars and spending our time and our energy.
The second half of the year, quite frankly, it depends. I don’t see us stopping with Merrimack. If the right opportunity presents itself, I don’t think anybody would be opposed to looking at a transaction. We certainly want to grow organically and find good quality people to bring on board. It’s still about growth throughout 2016 because I do believe it’s going to be a decent market for the next couple of years.
Makowiecki’s Top Five Sports Legends:
- Bobby Orr
- Larry Bird
- Carl Yastrzemski
- Tom Brady
- Tiger Woods